Executive boardroom at dusk overlooking the Albuquerque skyline and the Sandia Mountains

Licensed New Mexico cannabis operators only

New Mexico Cannabis CPA & Accounting Services

Specialized accounting, tax and financial advisory services for New Mexico cannabis businesses — accounting systems built around the financial realities of dispensaries, cultivators, manufacturers and other licensed operators.

Speak directly with a New Mexico Cannabis Accounting Specialist.

A boutique accounting and advisory practice built exclusively around licensed cannabis businesses in New Mexico — 280E tax strategy, inventory-grade bookkeeping, BioTrack reconciliation, CFO advisory and audit defense, delivered by people who work in this industry every day.

Practice focus
Cannabis only — no general business clients
Coverage
Every New Mexico license type, statewide
Method
Inventory-first accounting, documented positions

2026 Advisory

Schedule III Entity Restructuring

Following the federal reclassification of medical cannabis to Schedule III, the tax penalties of IRC Section 280E are deactivated for licensed medical operations. Our firm is actively structuring compliant expense apportionment and corporate entity models for dual-licensed New Mexico operators to lawfully maximize newly unlocked ordinary business deductions before upcoming state and federal filing deadlines.

Review Our 280E Restructuring Frameworks

Regulatory & accounting frameworks

Documented compliance architecture for New Mexico operators

RLD Cannabis Control Division Compliance

Our corporate compliance frameworks seamlessly trace operational data back through current Regulation and Licensing Department (RLD) Cannabis Control Division (CCD) mandates, aligned with Cannabis Regulation Act licensing protocols for cultivators, manufacturers, and retailers to ensure an unbroken regulatory audit defense trail.
Specialized Systems & Banking Architecture

Operating with tier-one accounting practice precision, we deliver specialized systems and software selection, high-risk merchant account setup, and dedicated banking solutions built exclusively for small- to medium-sized cannabis and hemp operators statewide.

Advanced IRC Section 280E & Cost Accounting Framework

Under IRC Section 280E and state tax rules, plant-touching operators face immense margin compression. We establish comprehensive, inventory-grade financial accounting and advanced cost management frameworks that meticulously isolate deductible cost allocations from disallowed corporate expenses.

Core practice areas

Where cannabis operators lose money — and where we work

Each practice area below has a dedicated page covering the methodology, the documentation standard and the questions New Mexico operators ask most.

Cannabis accountants reviewing financial reports and margin analytics on screen in a dark executive office overlooking the Sandia Mountains
Margin, inventory and tax exposure reviewed together — the way a cannabis engagement actually runs.

Technical depth

The subject matter this practice is built on

Cannabis accounting is inventory accounting under a punitive tax regime, layered on a state track-and-trace system and a cash-intensive operating environment. These are the areas that determine whether an operator keeps its margin.

Visit the resource center
  • IRC Section 280E
  • BioTrack track-and-trace
  • Cost of goods sold
  • Inventory accounting
  • Cannabis Excise Tax
  • Financial reporting
  • Cannabis payroll
  • Entity selection
  • IRS audits
  • Cash-intensive businesses
  • Internal controls
  • Regulatory compliance
  • Business scaling
  • Financial forecasting
  • Cannabis banking challenges

Industries served

Every CCD license type carries a different accounting problem

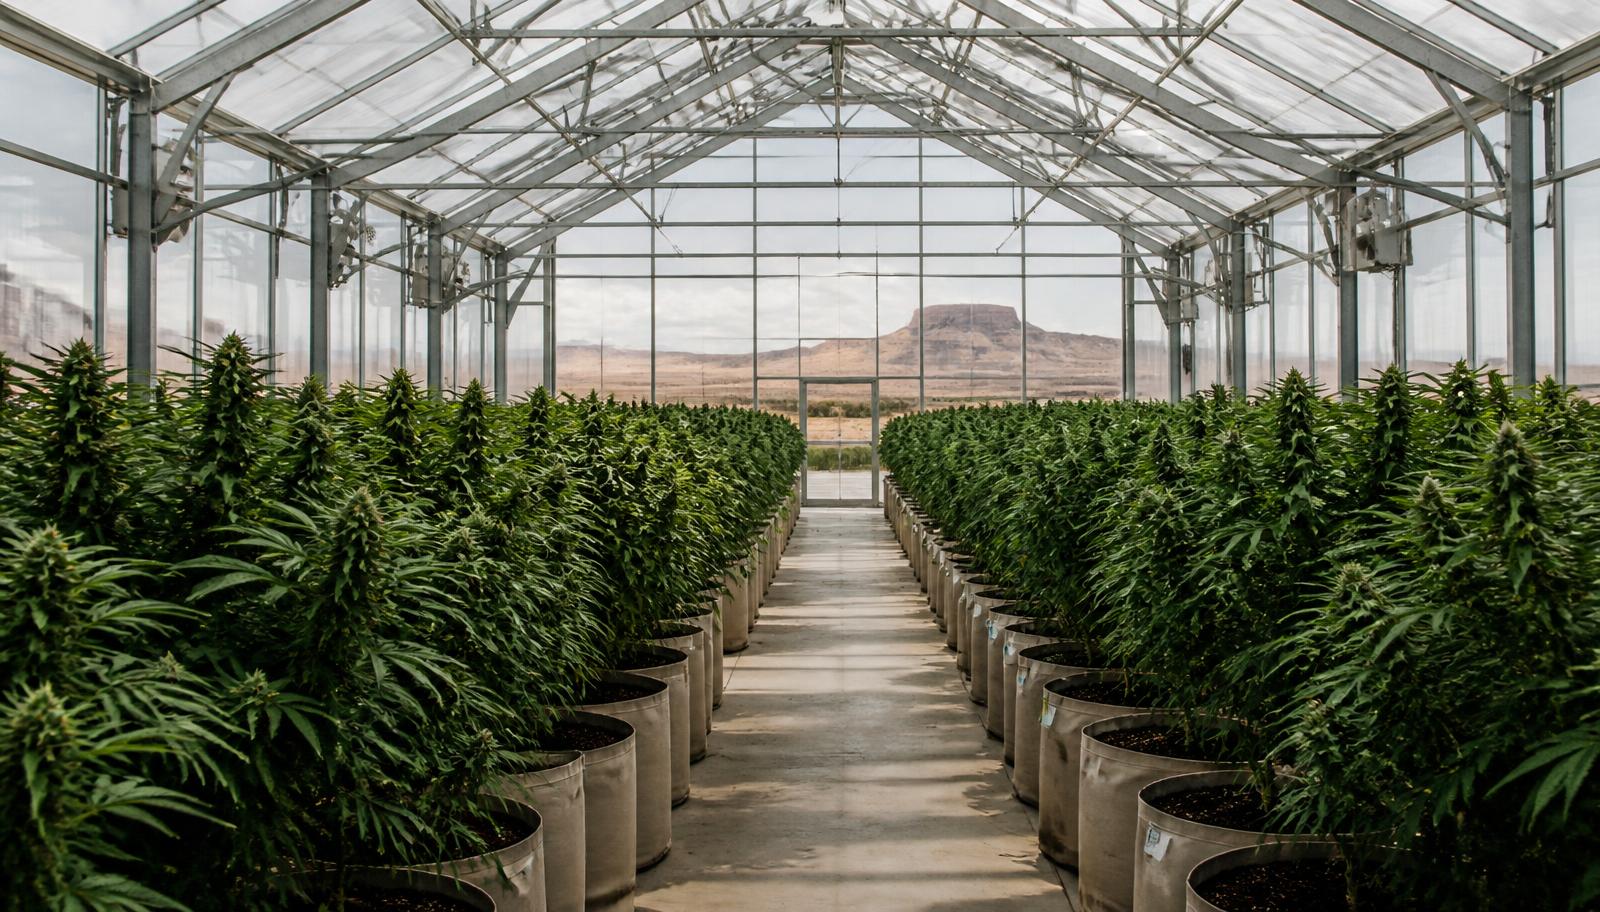
Licensed New Mexico cannabis cultivation greenhouse with long rows of plants and high-desert mesas visible beyond the glass
Cultivation, retail, manufacturing and distribution each carry a distinct inventory and 280E profile.

Full service list

Accounting, tax and advisory for licensed operators

Resource center

Educational guides for New Mexico cannabis finance

Bound accounting and tax reference volumes beside a printed financial report on a dark desk

Statewide practice

Cannabis CPA Services for New Mexico Businesses

A cannabis CPA helps cannabis businesses manage accounting, financial reporting, inventory, tax preparation and financial planning, while addressing the accounting and tax issues that are specific to the cannabis industry.

New Mexico cannabis operators generally need accounting systems that connect sales, purchasing, payroll, inventory, seed-to-sale records, financial reporting and tax workpapers into one coherent set of books. Those pieces live in different software. Nothing about them reconciles on its own, and the gaps between them are where margin, tax exposure and reporting reliability quietly erode.

Our practice is built entirely around licensed operators — retailers, producers, manufacturers, couriers, laboratories and the ancillary companies that serve them — across the whole state. Engagement scope varies: some clients need monthly bookkeeping and a clean close, others need CPA-level review, tax preparation and fractional CFO support layered on top.

How the pieces connect

  1. Sales
  2. Bank / cash
  3. Inventory
  4. Payroll
  5. Accounting
  6. Reconciliation
  7. Month-end close
  8. Financial reporting
  9. Tax / advisory / CFO

Definition

What Does a Cannabis CPA Do?

A cannabis CPA oversees bookkeeping and the month-end close, maintains inventory and cost of goods sold support, produces financial statements, prepares tax workpapers and returns, and advises on cash, budgeting and financial performance.

In practice, the role is defined by the engagement rather than the title. A smaller single-location retailer may need bookkeeping oversight and an annual return. A multi-entity producer may need full close management, inventory costing, management reporting and continuous CFO involvement. The responsibilities below describe the full range; most engagements use a subset.

  • Bookkeeping oversight and quality review
  • Month-end close on a published calendar
  • Financial statement preparation and review
  • Inventory accounting and inventory-to-ledger tie-out
  • Cost of goods sold support and documentation
  • Tax planning within current federal and state treatment
  • Tax preparation for the entity and, where applicable, owners
  • Payroll accounting and liability reconciliation
  • Cash flow planning and working capital analysis
  • Budgeting and budget-versus-actual reporting
  • Management reporting by location, entity or product line
  • Financial analysis supporting operating decisions
  • Multi-location and multi-entity accounting structure
  • Fractional CFO and executive financial support

Complexity

Why Cannabis Businesses Need Specialized Accounting

General accountants are perfectly capable of doing good work in this industry; the difference is how quickly someone recognizes the relationships that drive cannabis financial statements. In an inventory-heavy business, the income statement is largely a consequence of how inventory was tracked and valued. That single dependency ripples into gross margin, into tax workpapers, and into every management decision made from the reporting.

Dependency chain

  1. Sales
  2. Cash / bank
  3. Inventory
  4. COGS
  5. Payroll
  6. Financial reporting
  7. Tax workpapers
  • Inventory-heavy operations where most cost sits in product, not overhead
  • Cash management and deposit discipline in a payment-constrained environment
  • Limited or costly banking and payment processing options
  • Multiple disconnected operating systems that must be reconciled manually
  • Seed-to-sale records that document movement but not financial value
  • Federal tax treatment that raises the cost of weak inventory documentation
  • Entity structures that split operations, real estate and management functions
  • Multi-location operations needing comparable store-level reporting
  • Production accounting for cultivators and manufacturers
  • Management reporting expectations from owners, lenders and investors

Service hierarchy

Cannabis Accounting Services in New Mexico

Each service below has its own page covering methodology, deliverables and the questions operators ask most. Start where the pressure is — most engagements begin with bookkeeping or a cleanup, then add tax and advisory scope.

Foundation

Cannabis Bookkeeping in New Mexico

Cannabis bookkeeping is the disciplined recording and reconciliation of every financial transaction — sales, cash, purchases, payroll and inventory movement — so the month can be closed and the financial statements can be trusted.

Reliable financial reporting depends on reconciled accounting records. That is the whole argument for treating bookkeeping as an operating system rather than data entry. Sales summaries have to agree with deposits. Deposits have to agree with the bank. Vendor bills have to be recorded in the period the product was received, not when the invoice is finally paid. Payroll has to hit the right departments and locations so that production labor can be distinguished from selling and administrative labor.

  • Transaction recording from point-of-sale, purchasing and banking sources
  • Bank reconciliation for every account, every month
  • Cash reconciliation between register counts, deposits and the ledger
  • Accounts payable with bills recorded in the correct period
  • Payroll entries coded by department, function and location
  • Inventory-related entries for receipts, transfers, waste and adjustments
  • Balance sheet reconciliation, not just income statement review
  • Month-end close with a documented checklist and sign-off
  • Cleanup and catch-up work for books that have fallen behind

Bookkeeping flow

  1. Transactions
  2. Reconciliation
  3. Month-end close
  4. Financial reporting

Retail

Dispensary Accounting in New Mexico

Retail cannabis accounting is a volume problem before it is a technical one. Thousands of small transactions, daily cash handling, frequent inventory receipts and constant price and promotion changes mean errors compound quickly if the daily routine is not tight. The goal is a store-level profit and loss statement that an operator can read and act on within days of month end.

  • Daily sales recorded from point-of-sale summaries, not estimates
  • Deposit and cash reconciliation with documented variances
  • Inventory receipts, transfers and adjustments posted to the ledger
  • Cost of goods sold tied to actual product movement
  • Vendor bill entry matched to receipts
  • Payroll allocated to store and function
  • Gross margin reviewed by category and by store
  • Consolidated reporting across multiple retail locations

Retail flow

  1. Sales
  2. Cash / bank
  3. Inventory
  4. COGS
  5. Gross profit
  6. Financial reporting

Production

Accounting for New Mexico Cannabis Cultivators

Cultivation accounting is inventory accounting on a crop cycle. Costs accumulate over weeks or months before any product is sold, so the accounting question is which costs attach to the plants in process and which are period costs. Getting that right during the period — rather than reconstructing it at year end — is what makes cultivation reporting usable and cost of goods sold supportable.

  • Production cost capture by room, batch or harvest group
  • Cultivation labor separated from selling and administrative labor
  • Facility expenses including rent, utilities and environmental controls
  • Equipment purchases, depreciation and repairs
  • Seed-to-sale information used as an operational cross-check on movement
  • Inventory valuation as plants move from immature to harvest to finished goods
  • Cost of goods sold recognized when product is sold or transferred
  • Cash flow planning around long production cycles
  • Multi-facility reporting with consistent cost structure

Processing

Accounting for New Mexico Cannabis Manufacturers

Manufacturing adds a conversion step. Raw material enters, production labor and overhead are applied, and finished goods leave with a per-unit cost. Where production runs span period ends, work in process needs to be measured rather than assumed. Yield is the variable that most often explains a gap between expected and actual product cost.

  • Raw material receipts and consumption by production run
  • Production labor captured at the run or department level
  • Work in process measured where runs cross period boundaries
  • Finished goods costing on a consistent, documented basis
  • Packaging and componentry treated according to written policy
  • Yield tracking to explain variances in unit cost
  • Cost of goods sold by product line
  • Gross margin reporting that supports pricing decisions

Core discipline

Cannabis Inventory Accounting

Inventory quantities and financial inventory values answer different questions. One tells you what is physically on hand; the other tells you what it cost and what it will become when it sells.

Most cannabis accounting problems are inventory problems wearing a different hat. An operator can have an accurate operational count and still carry an inventory balance in the general ledger that has never been verified. Reconciling the two — repeatedly, in the period, at the item or lot level — is the single highest-value routine in cannabis accounting.

Inventory alignment

  1. Operational inventory
  2. Physical inventory
  3. Accounting inventory
  4. General ledger
  • Purchasing and receiving recorded at actual cost
  • Transfers between locations, rooms or entities documented both ways
  • Adjustments and waste posted with an explanation, not a plug
  • Physical counts on a defined cycle, with variance review
  • Ending inventory valued on a consistent, written method
  • Cost of goods sold derived from movement, not backed into
  • Gross margin reviewed against expectation each period
Read the inventory accounting guide

Measurement

Cannabis COGS Accounting

Conceptual relationship

Beginning inventory+applicable inventory activityending inventory=cost of goods sold

Cost of goods sold connects inventory accounting with gross-profit reporting. If the inventory balances at either end of the period are unreliable, cost of goods sold is unreliable too, and every downstream figure inherits the error: gross profit, gross margin, the income statement and the workpapers used to prepare the return.

Which costs are properly inventoriable is a documented accounting policy question, and the answer differs for a reseller and a producer. Financial accounting classification does not automatically establish federal tax treatment — that determination is made separately, in the tax workpapers, using the same underlying records.

Federal tax

Section 280E & Cannabis Tax Planning

Where Section 280E applies, ordinary business deductions are limited and cost of goods sold becomes the primary route by which costs reduce taxable income — which makes inventory records and cost documentation the center of any credible tax position.

Federal treatment of cannabis is time sensitive and has been the subject of ongoing administrative and legislative activity. We do not build client positions on the assumption that a particular outcome has already occurred. Depending on current federal tax treatment, the mechanics of a return can change substantially, but the underlying requirement does not: contemporaneous records that support how costs were classified.

From books to position

  1. Bookkeeping
  2. Inventory
  3. COGS support
  4. Tax workpapers
  5. 280E analysis

For cannabis businesses subject to Section 280E, the practical work is unglamorous: measured square footage, timekeeping that distinguishes production from selling activity, a written capitalization policy, and cost records assembled during the period. Those are the artifacts that hold up under examination. Tax positions are taken deliberately, documented, and reviewed as federal law changes.

Compliance

Cannabis Tax Preparation in New Mexico

A return is the output of a closed year, not a standalone exercise. Before preparation begins, the books have to be finished: every material balance sheet account reconciled, inventory verified, payroll tied to filings, fixed assets and debt rolled forward and equity activity accounted for. Only then do the workpapers mean anything.

  • Year-end close and cut-off review
  • Adjusted trial balance with supported entries
  • Balance sheet reconciliation for every material account
  • Inventory verification and valuation support
  • Cost of goods sold schedules with documentation
  • Payroll reconciliation to quarterly and annual filings
  • Fixed asset rollforward and depreciation schedules
  • Debt and intercompany balance confirmation
  • Entity and owner-level coordination
  • Tax workpapers assembled before the return is drafted

Preparation sequence

  1. Bookkeeping
  2. Reconciliations
  3. Adjusted trial balance
  4. Tax workpapers
  5. Tax return

Educational resources

New Mexico cannabis tax and accounting guides

New Mexico Cannabis Tax Guide

Operators looking for educational information about how cannabis taxation works in New Mexico can read our detailed guide. It covers federal treatment and Section 280E considerations, state excise and gross receipts mechanics, medical exemptions and the records that support each position. It is written to inform, not to replace an engagement.

Read the New Mexico Cannabis Tax Guide

New Mexico Cannabis Accounting Guide

Our accounting guide covers the mechanics behind the numbers: transaction-level cost isolation, inventory and cost of goods sold methodology, general ledger structure, the month-end close checklist and track-and-trace reconciliation. It is the reference companion to the commercial services described on this page.

Read the New Mexico Cannabis Accounting Guide

Financial leadership

Fractional CFO Services for New Mexico Cannabis Businesses

A fractional CFO turns finished accounting into forward-looking decisions: forecasts, budgets, cash plans, scenario analysis and management reporting, delivered part time.

The prerequisite is reliable history. Forecasting on top of unreconciled books produces confident numbers that are wrong. Once the close is dependable, the CFO conversation moves to where the business is going: what growth requires in working capital, which locations or product lines actually earn their cost structure, and what happens under each realistic scenario.

  • Financial forecasting on a rolling basis
  • Annual budgeting and variance review
  • Cash flow and working capital management
  • Scenario and sensitivity analysis
  • Capital planning and lender or investor reporting
  • Multi-location and multi-entity management reporting
  • Executive financial support for owners and boards

CFO progression

  1. Accounting
  2. Reporting
  3. Forecasting
  4. Decision support

Liquidity

Cannabis Cash Flow Planning

Profit and cash are not the same thing. A cultivator can post a strong month on paper while every available dollar sits in plants and packaging. Cash planning makes that distinction visible far enough ahead to act on it — usually through a rolling 13-week forecast updated against actuals each week.

Weekly cash view

Beginning cash+expected cash inexpected cash out=projected ending cash

  • Inventory purchases and production spending
  • Payroll and employer payroll costs
  • Tax obligations set aside as they accrue
  • Vendor payment timing and terms
  • Debt service and lease commitments
  • Capital expenditures and buildout draws
  • Working capital targets and minimum cash floors
Cash flow planning services

Output

Cannabis Financial Reporting

Financial reporting is what the rest of the accounting function exists to produce. The statements should be issued on a predictable date, be comparable period over period, and be granular enough that an operator can see which part of the business created the result.

  • Income statement with gross margin visible by line
  • Balance sheet with reconciled cash, inventory, payables and liabilities
  • Cash flow reporting distinct from profitability
  • Inventory reporting by location and category
  • Location-level and entity-level profit and loss statements
  • Budget versus actual with explained variances
  • Management reporting packaged for owners and lenders

Reporting chain

  1. Transactions
  2. Reconciliation
  3. Close
  4. Financial statements
  5. Management reporting

Labor

Cannabis Payroll Accounting

Payroll accounting is the bridge between labor and inventory. Wages, employer taxes and benefit costs need to land in the right department and location so production labor can be distinguished from selling and administrative labor, and so payroll liabilities reconcile to what was actually filed and paid.

  • Payroll journal entries recorded from provider reports
  • Gross wages split by department and function
  • Employer payroll taxes and benefit costs recorded with the related wages
  • Payroll liability accounts reconciled each month
  • Location coding consistent with the chart of accounts
  • Labor allocated to inventory where policy supports it
  • Tie-out to quarterly and annual payroll filings at year end

Systems

Track-and-Trace, Metrc & Cannabis Accounting in New Mexico

Seed-to-sale systems hold operational and regulatory data. Accounting systems hold financial data. A tracked quantity is not a financial inventory value, and operational records do not automatically replace accounting records.

Reconciliation is what connects them. Recorded movement in the track-and-trace system is compared with point-of-sale or production records, with physical counts, and with the inventory balance in the general ledger. Differences are investigated and explained rather than adjusted away. We are not affiliated with Metrc or with any track-and-trace vendor; we work with whichever system an operator is required to use.

Reconciliation path

  1. Seed-to-sale records
  2. POS / production records
  3. Physical inventory
  4. Accounting inventory
  5. General ledger

Scale

Multi-Location Cannabis Accounting

Multi-location accounting fails on inconsistency, not complexity. If two stores code the same cost differently, the comparison between them is meaningless and the consolidated view is worse than no view. The fix is structural: one chart of accounts, mandatory location coding, and a written method for allocating shared costs.

Consolidation model

  1. Location A / B / C
  2. Standardized accounting
  3. Location P&Ls
  4. Consolidated management view
  • A single chart of accounts used by every location
  • Location coding enforced at entry, not corrected later
  • Inventory tracked and counted by location
  • Payroll allocated to the location where the work happened
  • Shared and corporate expenses allocated on a documented basis
  • Store or facility level reporting on the same calendar
  • Cash handling procedures consistent across sites
  • Gross margin comparison used as an operating control

Structure

Multi-Entity Cannabis Accounting

Where operations, real estate, management and holding functions sit in separate entities, each one needs its own complete set of books. The most common failure is intercompany drift: a balance recorded on one side and never on the other, which makes consolidation impossible and complicates every return in the group.

Entity model

  1. Entity A / B / C
  2. Entity-level books
  3. Intercompany reconciliation
  4. Management reporting
  • Separate books, bank accounts and records for each entity
  • Clear ownership of inventory at all times
  • Intercompany transactions recorded on both sides in the same period
  • Shared expenses allocated under a written agreement
  • Debt, leases and related-party balances documented
  • Consolidated management reporting with proper eliminations
  • Tax reporting coordinated across the group

We handle the accounting and reporting consequences of a structure. Entity formation, ownership design and the legal terms of intercompany agreements belong with your attorney; we work alongside counsel rather than in place of them.

Entity structuring support

Remediation

Cannabis Accounting Cleanup

Cleanup work is common and nothing to be embarrassed about. Operators grow faster than their accounting function, a bookkeeper leaves, a system is migrated mid-year, and the books fall behind. The objective is a defensible starting point, not a perfect reconstruction of history.

  • Books behind by several months or more
  • Bank accounts that have never been reconciled
  • Cash discrepancies with no documented explanation
  • Inventory that does not tie to the general ledger
  • Aged accounts payable that no longer reflects real obligations
  • Payroll liabilities that do not agree with filings
  • Loan balances carried at incorrect amounts
  • Transactions mixed between entities or with personal accounts
  • Journal entries without supporting documentation
  • Year-end books that are not ready for tax preparation

Cleanup sequence

  1. Diagnose
  2. Reconcile
  3. Correct supported entries
  4. Close
  5. Report

Selection criteria

What Should a Cannabis Business Look for in a CPA?

The useful questions are about method and scope, not marketing. Ask how the firm handles inventory, what the close calendar looks like, what you will receive each month, and who you will actually be speaking with. These criteria apply whether or not you engage us.

  • Working knowledge of cannabis-industry accounting, not just interest in it
  • A clear method for inventory accounting and inventory-to-ledger tie-out
  • Comfort with cost of goods sold and how it is documented
  • Ability to produce financial statements on a predictable schedule
  • Relevant tax experience and a careful approach to positions
  • Multi-entity and multi-location experience where you need it
  • Willingness to work with your operational systems as they are
  • A written engagement scope with defined deliverables
  • Responsive communication and a named point of contact
  • Documentation discipline — support behind every material entry
  • The ability to explain your financial statements in plain language

Comparison

Cannabis CPA vs General Accountant

The distinction is not the label. Many general accountants do excellent work for cannabis clients, and a cannabis-focused firm without accounting discipline is worse than a careful generalist. What industry focus tends to buy is speed of recognition: fewer questions about how the operating systems work and more time spent on the accounting itself.

  • Familiarity with inventory-heavy cannabis operations
  • Experience with point-of-sale, cultivation and seed-to-sale systems
  • Fluency in cost of goods sold and its documentation
  • Awareness of Section 280E considerations where they apply
  • Retail dispensary accounting patterns
  • Cultivation and production accounting patterns
  • Manufacturing cost accounting patterns
  • Cannabis financial reporting expectations from lenders and investors

Scope

Cannabis Bookkeeper vs CPA vs Fractional CFO

These three roles are often confused, and their scopes overlap in practice. A small operator may get all three from one relationship; a larger one may use all three separately.

Comparison of cannabis bookkeeping, CPA and fractional CFO scope
BookkeepingCPA / accountingFractional CFO
Transaction recordingMonth-end and year-end closeForecasting and budgeting
Bank and cash reconciliationFinancial statement preparationCash and working capital planning
Accounts payable and payroll entryInventory and COGS reviewScenario analysis
Month-end supportTax workpapers and tax preparationManagement reporting
Document organizationAccounting analysis and policyFinancial leadership and decision support

Process

How Our Cannabis Accounting Process Works

No two engagements are identical — a single-store retailer and a three-entity producer need different work in a different order. The sequence below describes how we typically get from an initial conversation to reliable monthly reporting.

  1. 01Understand the business, its license types and how it operates
  2. 02Identify every entity and location in the group
  3. 03Review the existing books and the current close process
  4. 04Review the chart of accounts and coding discipline
  5. 05Review banking, cash handling and deposit procedures
  6. 06Review inventory systems and how movement is recorded
  7. 07Review payroll setup, coding and liability accounts
  8. 08Review tax status, filings and prior workpapers
  9. 09Reconcile material accounts and document the differences
  10. 10Establish a month-end close calendar and checklist
  11. 11Produce financial reporting on a predictable schedule
  12. 12Add tax, advisory or CFO support as the business needs it

Questions

Frequently asked questions about cannabis accounting in New Mexico

Statewide coverage

Cannabis accounting across New Mexico

Serving cannabis businesses across New Mexico. We support licensed operators in Albuquerque, Santa Fe, Las Cruces and communities throughout the state, with engagements delivered remotely and scheduled working sessions with your team.

  • Albuquerque
  • Santa Fe
  • Las Cruces
  • Rio Rancho
  • Roswell
  • Farmington
  • Clovis
  • Hobbs
  • Alamogordo
  • Carlsbad
  • Gallup
  • Los Lunas

Consultation

Talk with a New Mexico cannabis CPA

Bring your license types, current books and open deadlines. We will tell you what needs to happen first and in what order.